 IEEE/ICACT20250097 Slide.08
[Big Slide]
Oral Presentation
| Virual Oral Presentation Slide by Slide |
|
IEEE/ICACT20250097 Slide.08
[Big Slide]
| Oral Presentation |
|
|
|
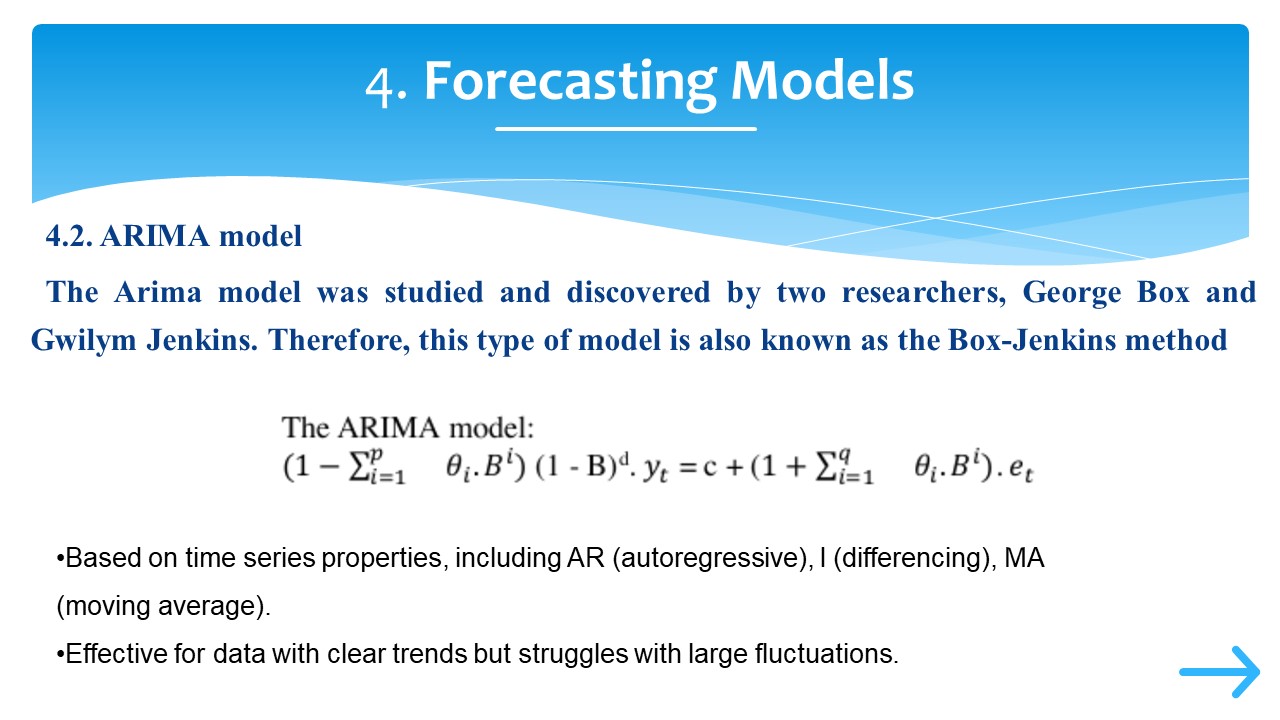
ARIMA, or the Box-Jenkins method, is a traditional time series forecasting approach that includes: AR (Autoregressive) using past values, I (Differencing) removing trends, and MA (Moving Average) smoothing out fluctuations. While effective for structured time series data, ARIMA struggles with large fluctuations and nonlinear economic trends. | |
| [Go to Next Slide] |