 |
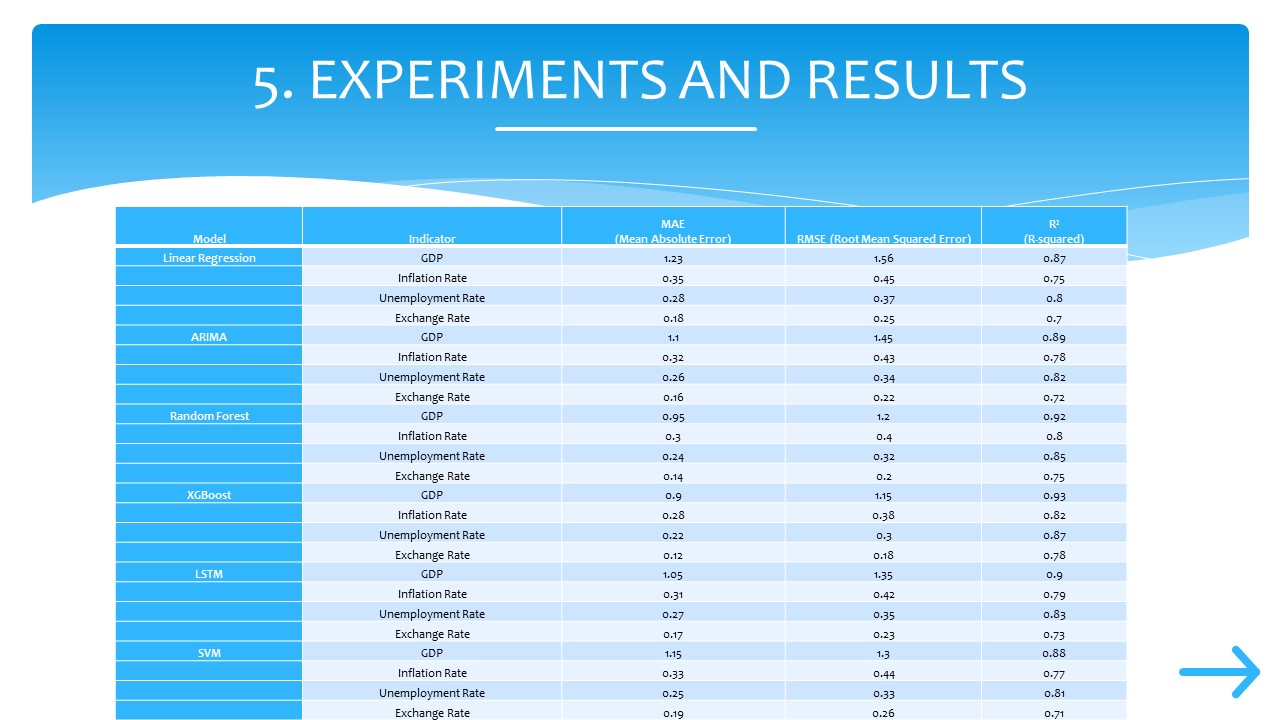
table shows the Mean Absolute Error (MAE) for each model across different economic indicators.
Random Forest and XGBoost outperform Linear Regression, ARIMA, LSTM, and SVM.
XGBoost, in particular, has the lowest error rates, making it the most reliable model for forecasting economic indicators.
the Root Mean Squared Error (RMSE) across different models.
XGBoost achieves the lowest RMSE for GDP, inflation, and unemployment rate predictions.
This suggests that XGBoost provides highly accurate forecasts for macroeconomic indicators.
Table presents the R-squared (R©÷) values for each model.
Higher R©÷ values indicate better model fit to the actual data.
Random Forest and XGBoost consistently show the highest R©÷ values, further confirming their effectiveness in economic forecasting. |
 IEEE/ICACT20250097 Slide.11
[Big Slide]